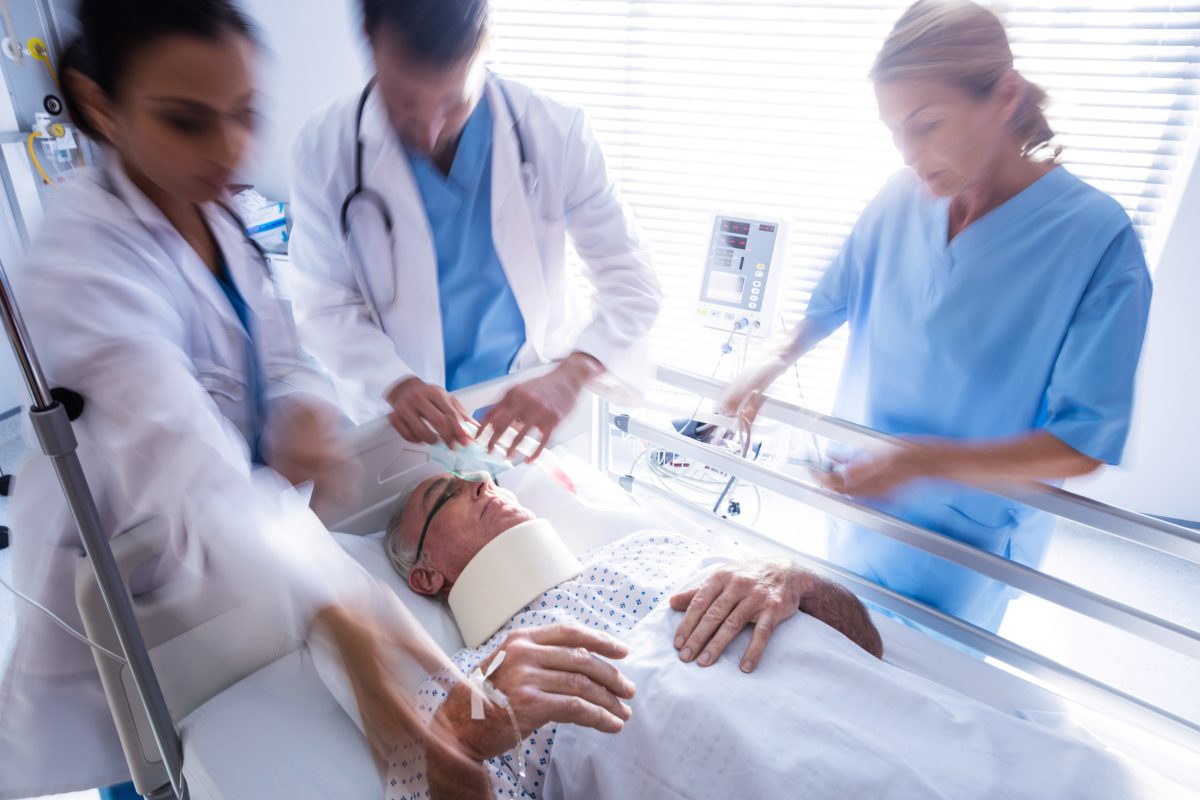
When you need medical attention for a sudden illness or minor injury, waiting several days for a primary care appointment may not be practical. Walk-in clinics and urgent care centers can provide convenient access to medical evaluation and treatment without the need for a scheduled appointment. However, understanding how your health insurance works before you visit can help you avoid unexpected costs and make the experience smoother.
For residents looking for urgent care New Hyde Park, knowing what their insurance covers, what they may need to pay, and which services are available can make a significant difference. Insurance policies vary considerably, so taking a few minutes to understand your benefits before arriving can help you make informed decisions about your care.
What Is Walk-In Care?
Walk-in care generally refers to medical services that do not require a previously scheduled appointment. Urgent care centers are designed to treat health concerns that need attention relatively soon but are not typically life-threatening emergencies.
Common reasons people visit urgent care include:
- Minor cuts, burns, and injuries
- Sprains and strains
- Cold and flu symptoms
- Sore throats and earaches
- Mild allergic reactions
- Fevers and infections
- Minor fractures or suspected fractures
- Vomiting or diarrhea
- Urinary tract symptoms
- Certain skin conditions
Urgent care can be a useful option when your regular doctor’s office is closed or when your condition requires more attention than a routine appointment can provide.
Does Insurance Cover Urgent Care?
Many health insurance plans provide coverage for urgent care visits, but the amount you pay can depend on the details of your individual policy. Your plan may have a specific copay for urgent care, while other plans may apply coinsurance or require you to meet a deductible first.
Before visiting an urgent care center, check your insurance policy or member portal for information about:
- Urgent care copays
- Deductible requirements
- Coinsurance percentages
- In-network and out-of-network coverage
- Covered diagnostic tests
- Prescription coverage
- Laboratory or imaging costs
Even when urgent care is covered, additional services performed during the visit may have separate costs.
Why In-Network Providers Matter
One of the most important insurance considerations is whether the urgent care center is part of your insurance company’s network.
Health insurance companies often negotiate rates with specific doctors, clinics, laboratories, and hospitals. These providers are considered in-network, and using them may result in lower out-of-pocket expenses.
If you visit an out-of-network facility, your insurance may cover less of the bill—or, depending on your plan, may not cover certain services at all.
You can usually check your insurance company’s website, mobile app, or member services phone number to determine whether a particular urgent care location is in-network.
What Should You Bring to Your Visit?
Having the right information with you can make the check-in process faster. Consider bringing:
- Your health insurance card
- A government-issued ID
- A list of current medications
- Information about allergies
- Relevant medical records, if available
- Details about previous treatments related to your current problem
- A payment method for any applicable copay or other charges
If you are visiting because of an injury, it can also be helpful to know when and how the injury happened.
Will You Have to Pay a Copay?
A copay is a fixed amount that you pay for a covered healthcare service. Some insurance plans charge a specific urgent care copay, while others may structure costs differently.
For example, your plan could require one amount for an urgent care visit and another amount for emergency room care. Because these amounts vary by plan, it is better to confirm your specific benefits rather than assume that every urgent care visit has the same price.
If you have a high-deductible health plan, you may be responsible for a larger portion of the cost until your deductible is reached.
What About Tests and Other Services?
An urgent care visit may involve more than a basic medical consultation. Depending on your symptoms, the provider may recommend diagnostic testing or other services.
These could include:
- X-rays
- Rapid flu or COVID-19 tests
- Strep tests
- Blood tests
- Urine testing
- Basic wound care
- Certain medications or treatments
Insurance coverage for these services can differ from the coverage for the visit itself. Ask whether a recommended test is covered and whether it is billed separately if you are concerned about costs.
Urgent Care vs. Emergency Room
Understanding when to choose urgent care and when to go directly to an emergency department is important.
Urgent care is generally appropriate for medical problems that require prompt attention but are not life-threatening. Emergency departments are equipped to handle serious or potentially life-threatening conditions.
Call emergency services or seek emergency medical attention for symptoms such as severe chest pain, significant difficulty breathing, signs of a major stroke, severe bleeding, loss of consciousness, or other potentially life-threatening conditions.
When you’re unsure, consider the severity and urgency of your symptoms rather than choosing a facility based solely on convenience or cost.
Questions to Ask Your Insurance Provider
If you want to understand your potential expenses before receiving care, consider asking your insurer:
- Is the urgent care center in my network?
- What is my urgent care copay?
- Have I met my annual deductible?
- What coinsurance applies to urgent care services?
- Are diagnostic tests covered?
- Could laboratory or imaging services be billed separately?
- Do I need prior authorization for any services?
- What happens if I need to be referred to another healthcare provider?
Writing down the answers can make it easier to compare your expected costs and avoid confusion later.
Making Your Urgent Care Visit Easier
A little preparation can save time. Before leaving home, confirm the clinic’s hours, check your insurance information, and make sure you understand your potential out-of-pocket costs.
You should also bring relevant medical information and clearly explain your symptoms to the healthcare provider. Mention when your symptoms began, whether they have become better or worse, and any medications you have already taken.
For people considering urgent care New Hyde Park, checking insurance participation and understanding your plan’s cost-sharing requirements before the visit can help reduce surprises when the bill arrives.
Plan Ahead for Your Next Walk-In Visit
Urgent care can provide a convenient middle ground between a primary care appointment and an emergency room visit. But convenience does not mean you should overlook the financial side of healthcare.
Knowing whether a facility accepts your insurance, understanding your copay or deductible, and asking about additional testing can help you make better-informed choices. Keep your insurance information accessible and review your plan’s urgent care benefits periodically, especially after changing insurance providers or plans.
Most importantly, remember that insurance coverage should never prevent you from seeking emergency medical attention when a serious or life-threatening condition occurs. For non-emergency concerns that require timely evaluation, understanding your insurance and preparing before a walk-in visit can make the process considerably easier.